
Summary of Dabur India’s Recent Performance
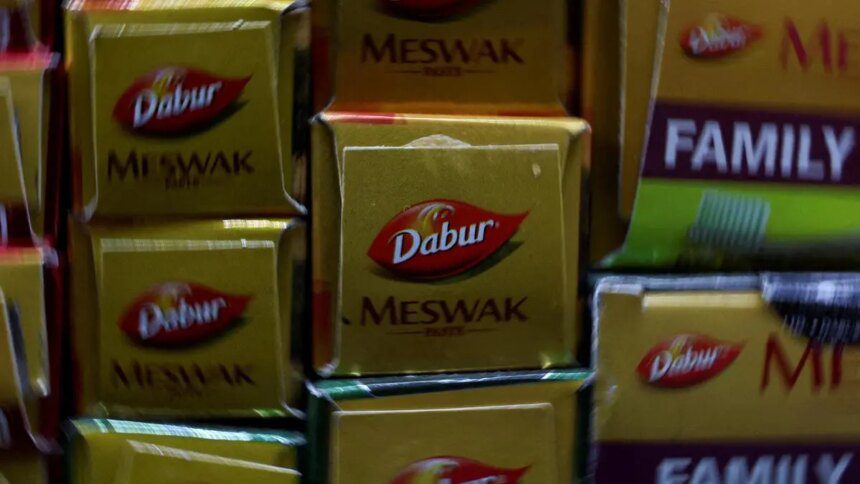
Dabur India’s shares experienced a nearly 2% drop on Thursday, trading at approximately ₹425 on the NSE. This decline comes amid concerns over elevated input costs and overall revenue performance despite the company reporting quarterly results that were generally in line with expectations.
Stock Performance and Market Context
The recent dip in Dabur’s stock price highlights a challenging year for the company, which has seen a significant 18% decline over the past year. The stock reached a 52-week low of ₹403.35 back in April, making its performance particularly underwhelming compared to the Nifty Midcap 50 index. Even though buy-side interest slightly exceeds selling pressure—with 56% buy orders versus 44% sell orders—the market sentiment has not shifted positively, as evidenced by the day’s decline.
Quarterly Financial Highlights
In its Q1 FY27 earnings report, Dabur reported consolidated revenue of ₹3,764 crore, marking a year-on-year increase of 10.6%. Operating profit showed robust growth at 11%, while net profit rose 15% to ₹591 crore. The FMCG volume growth within India was recorded at 5%, and international revenues increased by 15.5%. Home and Personal Care segments delivered strong domestic performance, achieving a growth rate of 12.3%. However, challenges such as unseasonal rainfall early in the fiscal year negatively impacted the beverages and glucose sales, although these sectors saw recovery later in May and June.
Analyst Insights and Future Projections
Market analysts have responded cautiously, with brokerage firms like Anand Rathi maintaining a “Buy” rating, although reducing the target price from ₹590 to ₹550 due to anticipated near-term volume growth challenges stemming from inflation. They value Dabur at 42x FY28 estimated earnings and project a revenue growth rate of 8.5% CAGR through FY28.
HDFC Securities adopted an “ADD” rating with a target at ₹465, reflecting a cautious stance due to weak execution metrics over a four-year revenue CAGR of just 4%. Equirus Securities also stands by an “ADD” rating with a target of ₹474, dubbing the current input cost inflation—around 8%—as a significant hurdle for maintaining margins. JM Financial, holding an “ADD” rating as well, has set a target of ₹490 and emphasizes the need for consistent revenue performance to encourage a positive re-rating of the stock.
Management’s Strategy Amid Challenges
Dabur’s management has set ambitious targets, guiding for low double-digit consolidated revenue growth in FY27, driven by pricing strategies, product innovation, and the ongoing overhaul of their go-to-market strategy via Project Saksham. The company has a solid net cash position of around ₹90 billion and is prioritizing investments in acquisitions, the establishment of a new unit in Tamil Nadu, and maintaining nearly full dividend payouts on its Indian profits, which reflects a strong commitment to shareholder returns despite operational hurdles.
What This Means
Dabur India’s fluctuating stock performance amidst rising input costs raises questions about the sustainability of its growth trajectory in a competitive FMCG sector. For Indian investors and consumers, the quarterly results showcase the balance between revenue growth and operational challenges. The cautious stance from analysts suggests a broader market sentiment that highlights inflationary pressures and their potential impact on consumer spending and company profit margins in the near term.
Frequently Asked Questions
What are the factors affecting Dabur India’s stock performance?
Key factors include elevated input costs, competition in the FMCG sector, and seasonality affecting product demand, particularly in beverages and glucose sales.
How did Dabur’s Q1 FY27 results compare to previous quarters?
Q1 FY27 results showed improved year-on-year growth with a 10.6% increase in revenue and a 15% rise in net profit, despite facing challenges due to unseasonal rainfall affecting sales in specific categories.
What is the management’s outlook for FY27?
Dabur’s management anticipates low double-digit consolidated revenue growth for FY27, supported by pricing strategies, product innovation, and efficiency improvements under Project Saksham.
How have analysts rated Dabur India post-results?
Analysts have provided mixed ratings, with most maintaining “ADD” or “Buy” recommendations, albeit at reduced target prices, citing challenges related to inflation and execution performance.